The Full Account: Arranging Travel Insurance When MS Shares the Itinerary
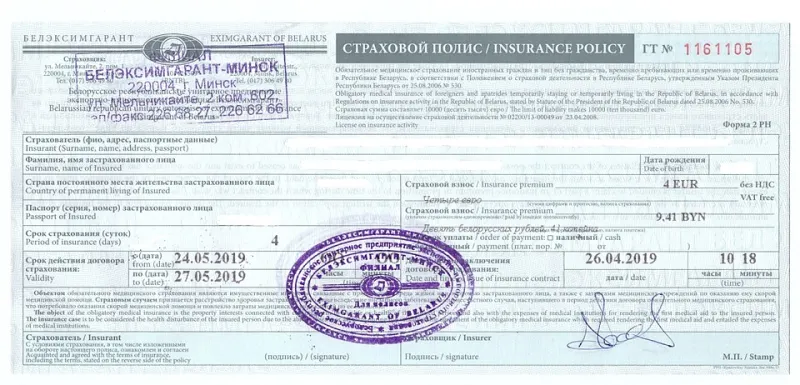
Photo: Rakoon, CC0, via Wikimedia Commons
Travel with multiple sclerosis asks for planning that begins well before the suitcase appears. Insurance is part of that planning, not an afterthought once flights and accommodation are booked. The aim is not to find the cheapest line on a comparison screen, but to arrange a policy that reflects the whole clinical picture and remains accurate as the trip approaches.
Why the full account matters
Insurance contracts depend on disclosure. When cover is arranged, the traveller is usually asked about existing medical conditions. Multiple sclerosis is one such condition, even when symptoms are currently mild or stable. The safer approach is to declare the diagnosis and answer the screening questions as fully as possible.
This is not about anticipating every event. It is about giving the insurer accurate information so that it can set terms and price the policy on a sound basis. If a material fact is omitted, an insurer may later reduce a claim or decline it altogether. The consequence can be financial and practical at the very point when support is needed.
What an insurer may wish to know
Medical screening varies between providers. Questions may cover the date of diagnosis, the type of MS, recent relapses, hospital admissions, mobility and the use of walking aids or a wheelchair. Insurers may also ask about medication, including disease-modifying therapies, steroids and symptom treatments. Other health conditions and any investigations still in progress can be relevant too.
Answers should be drawn from clinical records where possible rather than memory alone. If a question is unclear, it is reasonable to ask the adviser to explain what information is required. Telephone and online screening can both be used, but the date, provider and any reference number should be recorded. A short note made at the time is more reliable than a reconstruction months later.
Preparing before comparing quotes
A little preparation makes the process calmer. Before requesting quotes, gather the diagnosis date and type of MS, recent neurology or GP correspondence, a current medication list with doses, and details of any recent relapse or hospital care. It also helps to have the trip details to hand: dates, destination, total cost and whether cancellation cover is required.
Mainstream insurers may be able to screen MS, but specialist providers and brokers can be useful when the standard questions do not fit. General guidance from bodies such as the Association of British Insurers and MoneyHelper can help explain the principles without replacing the need to check a specific policy. Quotes should be compared on cover as well as premium, including medical expenses, repatriation, excess levels, cancellation terms and any activity or destination restrictions.
Reading the wording, not only the price
The policy wording deserves proper attention. Look for the clause on existing medical conditions and check that MS has been declared and accepted. Confirm whether the cover includes emergency medical treatment, repatriation and the 24-hour assistance line. If the trip involves a cruise, winter sports or travel outside Europe, check that these are included rather than assumed.
A UK Global Health Insurance Card can be useful for state-provided care in some European countries, but it is not a substitute for travel insurance. Cancellation cover also needs scrutiny. Some policies treat cancellation arising from a known condition differently from cancellation caused by an unexpected event. The definition of a trip, the excess and the evidence required for a claim should all be understood before purchase.
If symptoms or treatment change
A policy is based on the answers given when it was arranged. If medication changes, a relapse occurs, a hospital admission takes place or mobility changes before departure, the insurer should be contacted. An update may alter the terms or premium, but leaving the policy out of date may affect a future claim.
Written confirmation of any update is worth keeping. If a doctor advises against travel, the cancellation conditions and required documentation should be checked promptly. The same applies if a trip is shortened or rearranged because of MS. Early contact is usually more straightforward than waiting until a claim is made.
Keeping a simple record
A single folder, whether paper or on a phone, can hold the policy schedule, screening reference, declarations, insurer contact details and emergency number. Adding a current medication list and key clinical contacts makes the information easier to find if someone else needs to help.
Travel insurance is an administrative task, but it is also part of a steadier trip. An accurate declaration, a careful reading of the wording and a review before departure give the policy the best chance of doing its job. For anyone planning travel in 2026 and beyond, that quiet preparation is time well spent.